
Sector Performance - Telecom
Telecom: Explosive growth in subscriber base
- The launch of the various pre-paid schemes of low denomination and longer validation period, an aggressive expansion in the B and C category cities and the falling prices of handsets continued to drive the explosive growth in the subscriber base during the fourth quarter.
- During Q4FY2006 Bharti Tele-Ventures added more than 2.5 million subscribers. Expect the company to report a 42% growth in its net profit yoy, as its margins are likely to improve on the back of the success of its
"Lifetime free incoming" offer.

Sector Performance - Pharma
Pharma: Overall improvement in revenues
- This quarter will see a good improvement in the revenues and profit margins of various pharmaceutical majors as compared with their performance in Q4FY2005. That is because the domestic demand picked up in this quarter; in the same quarter in the previous year the domestic revenues of these companies had declined sharply as a result of de-stocking due to the implementation of VAT. Apart from this, the cost-cutting methods employed by various companies may also result in higher margins. The price erosion in the US markets continues but some of the big pharma firms like Ranbaxy
Laboratories and Lupin are expected to benefit from the increasing generic opportunities in FY2007 as blockbuster drugs like Pravastatin and Simvastatin go generic during the year. - For this quarter Cipla is expected to show a 28% growth in its net profit yoy. The growth would be driven primarily by the improvement in its domestic formulation business, a possible increase in the other operating
revenues and increased bulk drug exports due to the supply of new drugs to its partners in the regulated markets. - Cadila Healthcare is expected to show a substantial growth of 60% in the bottom line to Rs35.5 crore due to higher margins driven by increased domestic formulation sales and exports to the regulated markets.
- Unichem Laboratories, which is primarily a formulation maker, is also expected to benefit from the rising domestic demand and may show close to 30% growth in its net profit.
- For this quarter, Lupin is expected to show a strong growth in its profit after tax (PAT; over 80% yoy) due to a much better domestic demand for its goods and higher revenues from key molecules like Suprax in the regulated
markets as the flu season was in full swing during the quarter. - Ranbaxy Laboratories is also expected to show a 15% growth in its net profit due to better revenues from the Commonwealth of Independent States, Africa and Europe, and higher domestic formulation sales. Also lower costs due to lesser litigation costs, and stabilising research and development expenses are expected to bump up the margins sequentially.
- We expect Orchid Chemicals to show a steady 25% increase in its revenues led by the sale of the key cephalosporins in the US markets. We also expect its PAT to increase by more than 40% yoy (despite a deferred tax write-back of Rs9.7 crore in Q4FY2005 that inflated the PAT to Rs16.6 crore in Q4FY2005).
Sector Performance - Oil & Gas
Oil and gas: Hit by higher subsidy burden

- The provisional numbers for FY2006 reported by Oil and Natural Gas Corporation show that the company is likely to post a 25% year-on-year drop in its profits for Q4FY2006. This is despite the fact that the crude prices have gone up substantially over Q4FY2006. The drop is mainly on account of a higher subsidy burden (the subsidy burden for the full year will be provided in the last quarter).

- RIL is expected to report a flat bottom line, as its refining margins for Q4FY2006 are likely to decline by $1 a barrel. However, sequentially the growth is likely to be around 23.6%, as the company had undertaken a
50-day planned shut-down in Q3FY2006.
Sector Performance - Metals
Metals: Non-ferrous metals shine, ferrous metals dull
Non-ferrous
Non-ferrous
- Aluminum, copper and zinc prices created new highs in Q4FY2006, both in international and domestic markets. Also several price hikes were announced by the nonferrous metal companies during the quarter. These
developments should certainly have a positive impact on the Q4FY2006 performance of the non-ferrous companies. - Hindalco Industries raised aluminum prices by 16.2% or Rs17,000 per tonne in the quarter. The aluminium business saw a healthy volume growth on the back of a strong demand for the white metal. However, only a marginal recovery in copper production as compared with that in Q3FY2006 would offset the gains from the aluminum business and the company's earnings are expected to grow at 10.4%.
- Sterlite would benefit from an increased copper and aluminum production, higher TC/RC margins and excellent results from Hindustan Zinc. Its aluminum production business would benefit from the partial commissioning of the expanded part of the Korba facility.
- A strong demand for alumina coupled with supply shortages caused National Aluminium Company to revise its alumina prices by 16% during the quarter in line with the international prices. This coupled with a strong volume growth in its alumina and aluminum production business is likely to drive the OPM and profitability of the company in Q4FY2006.
- Zinc was the commodity in action during Q4FY2006. Hindustan Zinc raised zinc prices by 25.9% or Rs29,000 in the quarter. With a healthy growth in its realisations and volumes, the company should report the best growth in earnings.132%.among the entire metal pack.
- Ferrous metal companies were hurt by the overall uncertainty pervading in the international markets during the quarter which resulted in a sharp drop in the price of hot-rolled coils, sponge iron and pig iron. Respite came in March 2006 in the form of rising prices but the effect of the same will be felt only in Q1FY2007.
- Expect Tata Steel to end the quarter with a marginal drop of 3.4% in its profits. The benefit of higher metal production is likely to get negated by a lower average realisation in the quarter.
Sector Performance - Information Technology
Information technology: Strong sequential growth in revenue

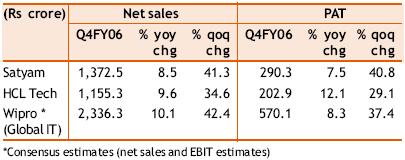
- The average sequential revenue of the sector is estimated to grow at 6-10% in Q4FY2006 and the growth rate is marginally lower than that in the previous quarter but higher than the market's expectation at the beginning of the quarter. The average top line is expected to be driven by the 7-11% growth in the volumes (a higher sequential volume growth as Q3 has less number of working days) during the quarter.
- The appreciation of the rupee against all the other major currencies would adversely affect the sequential growth in the average revenue.
- Expect the revenue of Satyam Computer, HCL Technologies and Wipro to record a strong sequential growth of 8.5%, 9.6% and 10.2% respectively.
Sector Perfromance - FMCG
FMCG: Volume growth continues
- Backed by a pick-up in the rural demand, FMCG sector has seen a gradual improvement in the volume growth every quarter. The revenue growth for the current quarter is likely to be in the higher double-digit range.
- Expect the earnings of the market leader, Hindustan Lever, to grow by 27% yoy backed by a strong volume growth and price hikes in key product segments.
- ITC's profits are expected to grow by a strong 33% yoy. Expect the growth to be broad based. ITC had recently effected price hikes in its cigarette business. Its non-FMCG businesses have also grown well.
- Expect Godrej Consumer Products to report a 20% revenue growth with its personal care segment continuing to record a strong growth. The net profit growth is likely to be in the 41% range as the vegetable oil prices have been stable and there has been a shift in the company's product mix in favour of the personal care products.
Subscribe to:
Posts (Atom)