- During Q4FY2006, the cement dispatches of all the three major players, Associated Cement Companies, Gujarat Ambuja Cement and the Aditya Birla Group, saw a handsome growth. The average price realisation also grew by a strong 8.6% in the quarter.
- Expect the cement division to be the top performer for Grasim Industries; however the poor performance of the viscose staple fibre and sponge iron businesses will drag down the profitability of the company.
- Expect Madras Cements Ltd (MCL) to register a healthy volume growth of 30% yoy in Q4FY2006 on the back of a strong demand in south India. With the elections round the corner, cement prices in the southern region declined by 3-4% yoy. However the implementation of the flat tax rate of 14.5% in Tamil Nadu as against the effective tax rate of 23% shall nullify the effect of the lower cement prices in the south. Consequently, expect MCL to register a strong 45% growth in its Q4FY2006 earnings.
- Shree Cement is likely to report a healthy volume growth of 11-12% driven by the commissioning of its new 1.2- million-tonne cement plant. This coupled with the impressive growth of 10-12% in the realisation is likely to lead to a high 50% growth in its operating profit.

Sector Performance - Cement
Cement: Healthy growth in dispatches of top three

Sector Performance - Capital Goods and Engineering
Capital goods and engineering: Growth continues
- The Index of Capital Goods grew by 16.8% for the year till January 2006 as compared with a growth of 13.1% in the same period last year. Considering the economy is witnessing a period of investment boom, expect a similar growth in the January-March 2006 period.
- Crompton Greaves should report a good performance in Q4FY2006 on the back of a strong order booking in the industrial system and power system divisions. Expect an improvement in the performance of its 100% subsidiary, Pauwels Transformers, during the quarter.
- In the wake of the receding input cost pressure, Thermax should continue with its margin expansion and report an improvement in its stand-alone operating profit margin (OPM). This coupled with a strong order booking should result in a healthy growth in its stand-alone earnings. We expect the loss-making subsidiary, ME Engineering, to show an improvement in its performance and drive the consolidated earnings of the company.
Sector Performance: Banking - Rising interest rates to hurt
BANKING Sector Performance

- The loan book of scheduled commercial banks has grown by 33.3% during the quarter up to the week ended March 17, 2005. However, the growth in the net interest income (NII) is likely to be moderate. That is because the net interest margin is expected to be under pressure owing to a rise in the borrowing rates after the severe liquidity crunch of the fourth quarter.

The mark-to-market losses of the banks are also expected to go up, as the government bond yield has remained flat over the last quarter.- State Bank of India (SBI) is likely to report a decline in its NII as the margin pressure is likely to continue. The bank's borrowing cost is likely to go up in the wake of the redemption of the India Millennium Deposits in December 2005. Also in Q4FY2005, SBI had earned an interest income on the income tax refund which will result in a lower NII this quarter. The net profit growth is likely to be flat as the other income is also expected to be lower due to a lower income from the government business.
- ICICI Bank is likely to report a strong growth in its NII backed by a strong loan growth. The equity issuance by the bank in the last quarter should help it to achieve a robust growth in its loan book.
Sector Performance: Automobiles - Two-wheelers to outperform
AUTOMOBILES Sector Performance
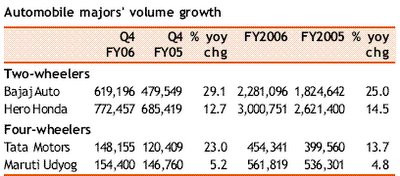
- The two-wheeler segment continues to outperform the four-wheeler segment in terms of volume growth.
- Among the two-wheelers, Bajaj Auto leads the sector with a 29.1% growth for Q4FY2006 and a 25% growth for FY2006. The growth has picked up strongly in Q4FY2006 after a subdued Q3FY2006.
- The four-wheeler segment, mainly the passenger vehicle segment, has been growing selectively. The growth in the volume of the segment leader, M-800, has been declining of late and is expected to be lower for the quarter, thereby putting a damper on the segment's growth. However, the decline in the sales of Maruti Udyog's M-800 model is expected to be offset by the pick-up in the offtake of Alto and Swift. The increased proportion of these higher-end models is expected to result in higher realisations and margins.

- The margins will be maintained during the quarter for both the segments, as the high prices of non-ferrous metals will be set off by the lower steel prices.
- The commercial vehicle segment has managed to maintain a double-digit growth rate on a high base of last year and this growth rate is expected to be maintained for the rest of the year.
Q4FY2006 Earnings Preview
Key points


- The domestic demand-driven story is likely to continue considering that the growth in the earnings of the Sensex is expected to have been led by companies from the automobile, cement, capital goods and fast moving consumer goods (FMCG) sectors in Q4FY2006.
- Pharmaceutical companies are also expected to show arobust growth for this quarter, since for these companies the growth in the same quarter last year was affectedby value-added tax (VAT) related issues.

- For the fourth quarter, the earnings growth rate of theSensex companies is likely to be 14.0% year on year(yoy), slightly lower than the growth rate of 14.3% inQ3FY2006.
- The lower growth can be attributed primarilyto the expectations of a flat growth in the bottom lineof Reliance Industries Ltd (RIL).
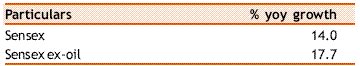
The FY2006 earnings of the Sensex companies areexpected to grow at 21.5%. Excluding the oil companies(RIL and Oil and Natural Gas Corporation) the growth islikely to be 22.6% for the quarter.
I will, in the subsequent posts, discuss performance of each sector.
Stock Reco's for Upcoming Week
Maruti Udyog
Recommendation: Hold
Price target: Under review
CMP: Rs 870
- Owning all of MSAILMaruti Udyog Ltd (MUL) would be buying out the entire stake of its joint venture partner, Suzuki Motor Company, Japan (SMC), in Maruti Suzuki Automobile India Ltd (MSAIL) and merging the subsidiary with itself.
- At present, MUL holds a 70% stake in MSAIL whereas SMC holds the remaining 30%. We view MUL’s decision to buy out the entire SMC stake in MSAIL as a big positive for the domestic car major.
Reliance Industries
Recommendation: Buy
Price target: Rs 870
CMP: Rs 847
- I had mentioned earlier that the forthcoming initial public offering of its subsidiary Reliance Petroleum will add an upside of approximately Rs75 per share to RIL’s value.
- The recent stake sale by RIL to global oil and gas major Chevron just vindicates our view.
Monetary policy review
The Reserve Bank of India (RBI) will announce the Monetary and Credit Policy statement for 2006-07 on April 18, 2006. We discuss below our expectations of the apex bank.
- The RBI increased the benchmark repo and reverse repo rates in two consecutive moves during the last two quarterly reviews. In the forthcoming policy statement the RBI will have to strike a balance between the tightening liquidity and the surging oil prices as well as the rising asset inflation.
- We do not expect the RBI to tinker with the cash reserve ratio (CRR) as the liquidity situation is easing out. Nevertheless the same may be taken up in the quarterly review of the policy some time in July 2006.
- The RBI may announce some more safety measures in relation to the banking sector’s exposure to the capital market and the real estate sector.
- The central bank’s inflation guidance for FY2007 is likely to remain at 5.0-5.5%.
Subscribe to:
Posts (Atom)