Stock Reco's for This Week

Godrej Consumer
Target Price = Rs 912
  • Godrej Consumer Products Ltd (GCPL) is a big beneficiary of the expected consumption boom in India. A rising proportion of the middle-income families will translate into a strong demand for its products like soaps, hair
    colours and toiletries.
  • The market share gains in the soap business through the consolidation of brands (Godrej No 1) and the launch of new products will lead to a robust growth, outpacing the growth in the soap market.
  • The hair colour segment offers huge opportunity owing to its under-penetration and a strong 16-20% compounded annual growth rate (CAGR). GCPL with its dominant market share and a quality product basket should reap handsome gains.
  • Cash flows are expected to grow at a CAGR of 22% in the FY2005-08 period; the same will be deployed in purchasing growth by augmenting capacities and through inorganic growth aspirations.
  • GCPL trades at a PER of 31.7x its FY2007E earnings in view of the inorganic growth triggers and the shareholders' value maximising strategy.

Satyam Computers
Target Price = Rs 900
  • Unlike some of its front-line peers, Satyam has shown a healthy and consistent sequential growth over the past six to eight quarters.
  • Despite the continued losses of its subsidiaries and the other cost pressures, the company.s top line growth has been accompanied by stability in profitability.
  • It has levers to support its profitability like the turn-around in its subsidiaries, the broadening employee base, an increasing offshore contribution etc which would limit any downside to its profitability.
  • It is ahead of some of its peers in terms of bagging business in the recently announced large outsourcing deals.
  • It trades at attractive valuations of 20.7x its FY2007E earnings, which is still at a considerable discount to some of its peers.

ITC
Target Price = Rs 220
  • ITC is the undisputed market leader in the cigarette business in India. Over the years ITC has gained substantial pricing power in the market and has been posting a good volume growth in the business.
  • ITC has diversified its revenue stream by successfully channelising the huge cash flows generated from the cigarette business into new and upcoming businesses like hotels, fast moving consumer goods (FMCG), paperboards and agri-marketing.
  • ITC's huge investment in these businesses has now started reflecting in a robust growth in the revenues as the profits.
  • ITC's venture into agri-marketing through e-Choupal is now set to replicate the urban mall mania in rural areas through Choupal Sagar. Choupal Sagar is expected to be a major revenue and profit driver for ITC over the long term.
  • With an earnings CAGR of 23.4% over FY2005-07E the stock is attractively quoting at a PER of 28.3x its FY2007E earnings.

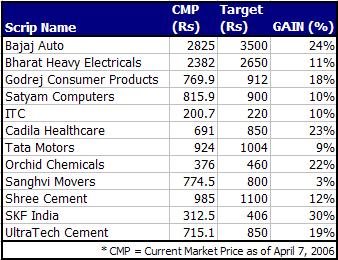
Stock Reco's for this Week

Bajaj Auto
Target Price = Rs 3500
  • With the help of new product launches over the last few years, Bajaj Auto Ltd (BAL) is well poised to take advantage of the secular growth in the two-wheeler market. BAL is likely to consolidate its position in the market further as the new product launches continue.
  • The three-wheeler segment, which is a high-margin business, is turning around after a brief lull. The changes in the regulatory regime in favour of vehicles using cleaner fuel is likely to boost the demand for threewheelers
    where BAL is the undisputed leader.
  • With the increased contribution of high-margin vehicles and the softening of the prices of steel, BAL is expected to see a 20% compounded annual growth in its earnings over FY2005-07E.
  • The stock is currently quoting at a PER of 19.8x its FY2007E earnings. The investment on the company.s books (Rs 648 per share) and the insurance subsidiaries (Rs 920 per share) add substantial value to BAL.s fair value.

BHEL
Target Price = Rs 2650
  • Bharat Heavy Electricals Ltd (BHEL), a leading supplier of power equipment, will be the prime beneficiary of a four-fold increase in the investments (Rs 500,000 crore in the 11th Five-Year Plan as against Rs 112,000 crore in
    the 9th Five-Year Plan) being made in the power sector. .
  • BHEL's current order book of Rs 37,500 crore, ie 3.0x its FY2005 revenue, provides high earnings visibility.
  • The power ministry has proposed around five ultra mega power projects entailing a capacity addition of 20,000MW (4,000MW x 5) with the combined turnkey value of at least Rs 80,000 crore.
  • BHEL.s recent technology transfer agreement with Alstom for design and manufacture of large-sized (500MW+) super-critical boilers will enable it to bid for the ultra mega power projects. I expect BHEL to bag a fair share out of this huge Rs 80,000-crore potential investment, which in turn will maintain the growth momentum in the company.s order book.
  • The stock trades at a PER of 21.4x its FY2007E earnings. BHEL's valuation looks attractive as compared with that of its peers, such as Siemens, ABB and Larsen and Toubro.

TOP PICKS & PERFORMANCE OF MY RECOMMENDATIONS

Hello Dear Users,

As a regular performance checking of my recommendations, kindly find below Performance Status of some of my TOP RECOMMENDATIONS:


I thank you for all your support!

Best Regards,
Gemini

Stock Reco's for Today...

Container Corporation of India
Recommendation: Book profit
CMP = Rs 1,413
  • The stock has appreciated by 28% since then and close to our price target of Rs1,450. We recommend investors to book profit.

Emco

Recommendation: Book profit
CMP = Rs 800
  • The stock has appreciated by 131.8% since then and achieved our price target of Rs600. We recommend investors to book profit.

Stock Reco's for Today...

Madras Cement

Recommendation: Buy

CMP = Rs 2388

Price target: Rs 3,250

  • At the current market price of Rs2,388 the stock is discounting its F2007 earnings by 21x and its FY2008 earnings by 15.7x.
  • The stock is trading at attractive valuations on EV/tonne basis with a value of US$116 for FY2007 and of US$109 for FY2008.
  • At this price target the stock will be discounting its FY2008 EBIDTA by 11x and will be trading at EV/tonne of US$146.

McDowell & Company

Recommendation: Book Profit

CMP = Rs 878

  • The stock has appreciated by 86% since then and achieved our price target of Rs750. We recommend investors to book profit.

Stock Reco's for Today...

UltraTech Cement
Recommendation: Buy
CMP = Rs 704
Price target: Rs 850
  • At the current market price of Rs704, UltraTech Cement is discounting its FY2008 earnings by 26.8x and 11.8x its FY2008 earnings before interest, depreciation, tax and amortisation (EBIDTA).
  • On an EV/tonne basis the stock is trading at an attractive valuation of US$118 per tonne of cement. This is a huge discount to its peers like ACC and Gujarat Ambuja that are trading at valuations in excess of US$150 per tonne of cement.
  • I believe the valuations are very attractive considering the company’s high leverage to the prices of cement. Consequently, we are revising our price target for the stock to Rs850, at which it will be trading at US$140 per tonne of cement, which is still a discount to the valuations commanded by its peers.

Jaiprakash Associates

Recommendation: Buy
CMP = Rs 480
Price target: Rs 650
  • At the current market price of Rs480, Jaiprakash Associates is discounting its FY2007 earnings by 21.1x and its FY2007 EBIDTA by 7.6x.
  • I have valued the company on the sum-of-parts basis. I have valued the cement business at the rate of US$140 per tonne of cement and the Engineering & Construction business at a multiple of 7 on FY2008 EBIDTA. Consequently we are revising our target for JAL to Rs650.

Stock Recommendations for Today...

Marico Industries
Recommendation: Buy
CMP = Rs 569
Price target: Rs 635


Godrej Consumer Products
Recommendation: Buy
CMP = Rs 760
Price target: Rs 912
  • The visibility in the revenues and earnings has been the strongest in the recent years for the fast moving consumer goods (FMCG) industry in general and for Godrej Consumer Products in particular.
  • The demand outlook is strong in view of the new breed of consumers ie semi-urban and rural consumers who have joined the consumption fray and have given the much needed spark to the industry.
  • Given these vital fundamental changes, the valuations are fast changing. Comparable companies in the FMCG sector are already commanding higher valuations with the 2-year average industry price/earnings (P/E) multiple reaching +24-25x. GCPL, which trades at P/E multiple of 20.8x FY2008E consolidated earnings is still available at a discount of 20% to the average industry P/E.
  • Considering the significant room for growth within the core businesses (hair care and toiletries businesses) and the entry in the international space through Keyline Brands, we have confidence in GCPL's long-term growth prospects.
  • I am revising our price target for GCPL to Rs912, at which price the stock will discount its FY2008E consolidated earnings by 25x, in line with the industry.
 

© blogger templates 3 column | Make Money Online